

A broader catch-up rally ahead?
We head into earnings season with a highly concentrated US equity market led by tech and AI. If the rest of the market reports strong profits, there’s scope for a broadening out rally.
Published: OCT 19, 2026
A recurrent theme of recent years has been extreme levels of concentration within the US equity markets. The Mag 7 account for roughly one-third of the market cap of the S&P 500 and AI-related stocks hold 45%. The equal-weighted S&P 500, by contrast, saw a set of seven-straight weekly losses recently, something previously only seen in the 2002 and 2022 bear markets.
Earnings season is now at hand, and we are expecting to see earnings growth rates of nearly 30%; if so, it will be the third straight quarter with growth above 25%. Lately, tech stocks have been the main beneficiaries of this earnings growth; if the rest of the market reports handsome earnings this quarter, a catch-up trade could result.
The big question mark in the next few weeks is the US midterm elections. Divided government, and the ensuing gridlock, would likely be popular on Wall Street. One can imagine AI stocks could face increased scrutiny under the new Congress. Even if more symbolic than substantive, that might be enough to help prompt an overdue broadening out.
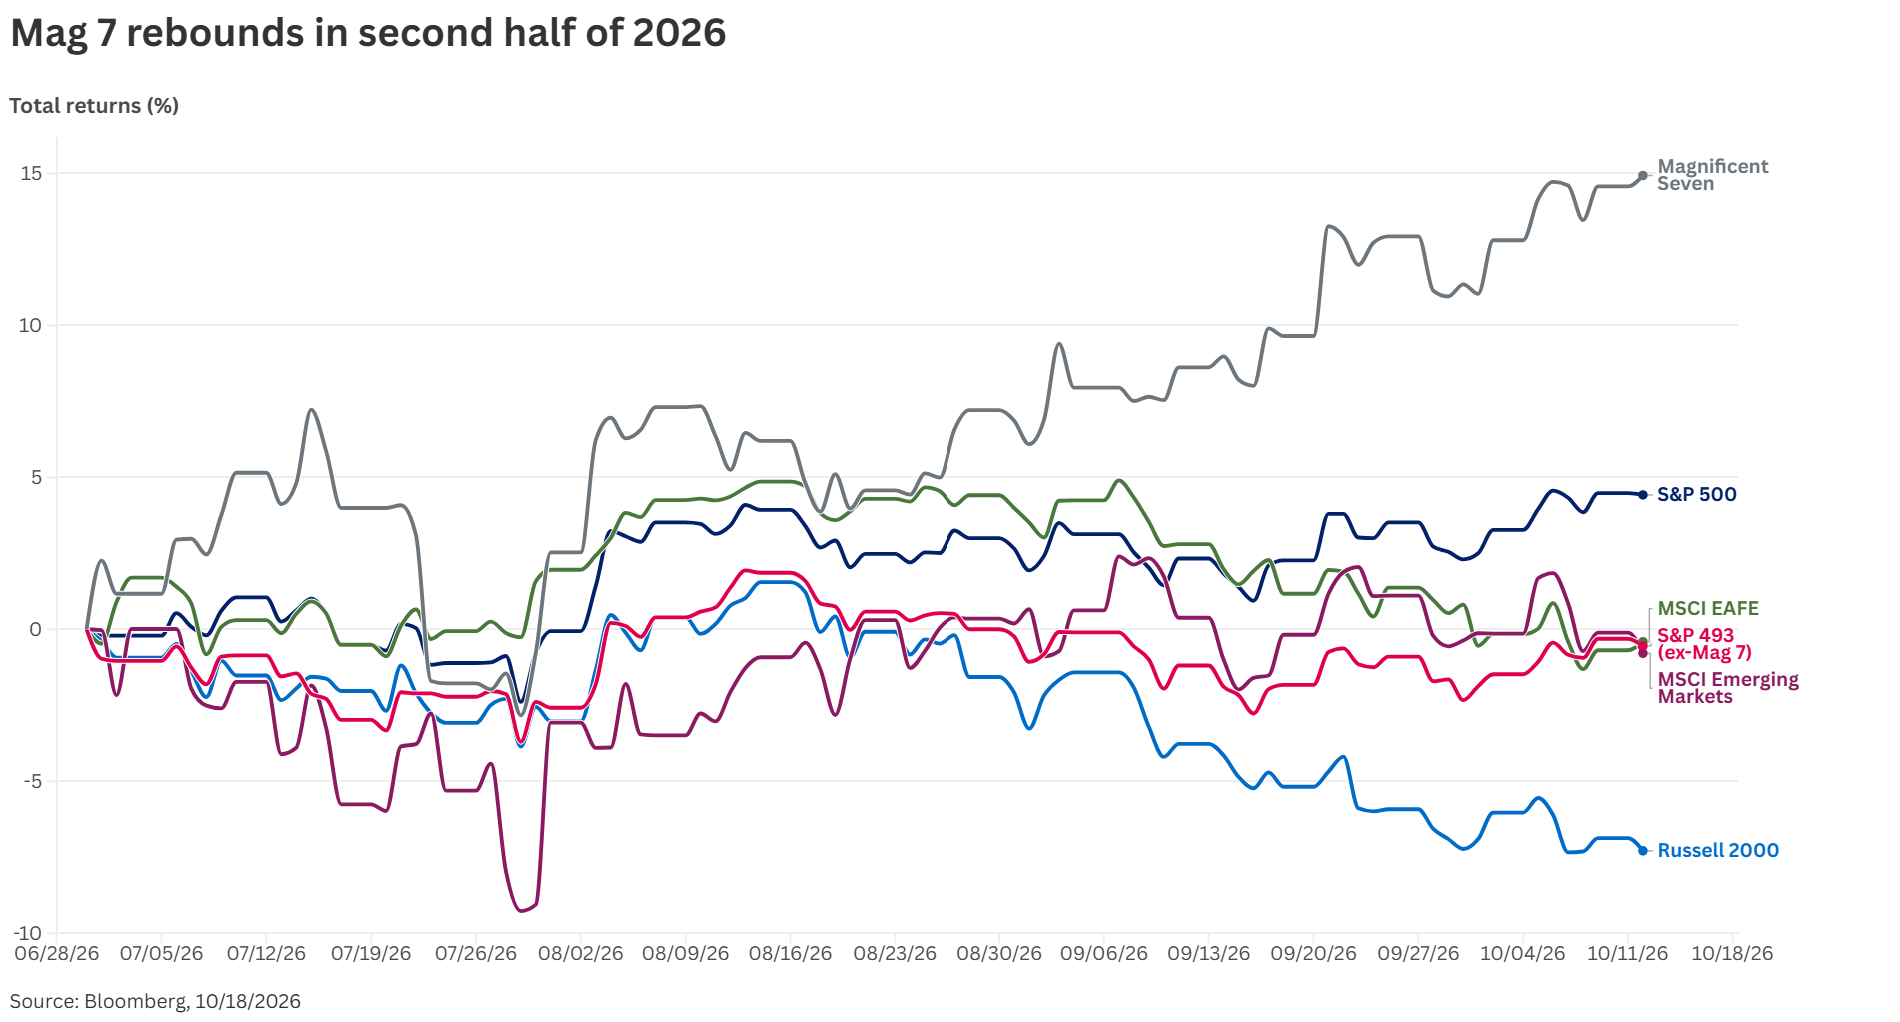
Magnificent Seven: Moniker for seven mega-cap tech-related stocks Amazon, Apple, Google-parent Alphabet, Meta, Microsoft, Nvidia and Tesla. Past performance is no guarantee of future results. For illustrative purposes only.
Our outlook:
If the market broadens out, we might see the largest firms experience more modest performance while other stocks start to catch up. Active management can be particularly important at such a time, as the index may fail to capture the churn within the market as a whole. Disciplined US and international equity strategies could benefit from a catch-up rally.
- Resilient growth, slow disinflation scenario — Inflation moderates gradually, growth slows but stays positive, and the labor market cools but remains healthy. Potential portfolio considerations: We believe diversified equities could work well, with a tilt toward large-cap quality and international names potentially benefiting from stable global growth; small caps may have less support without a stronger growth catalyst; emerging-market equities look attractive. In fixed income, short-duration strategies (roughly one- to three-years) allow a nimble stance without betting on rate-cut timing, and investment-grade credit is favored over high yield given moderate growth and contained spreads. In our view, emerging market debt can perform reasonably well if the US dollar stays range-bound.
- Inflation persistence scenario (stagflation lite) — Growth weakens while inflation remains sticky from energy costs, wages, tariffs, and geopolitics. Potential portfolio considerations: Historically, large-cap, quality stocks with pricing power tend to hold up better against margin pressure; value tends to outperform growth, and small caps may be more vulnerable to tightening conditions. Ultra-short and floating-rate fixed income reprices automatically if the Fed hikes, offering a potential hedge, while investment-grade credit may be preferable to high yield for its stronger balance sheets. Emerging market debt is likely to lag, as sticky inflation and a firmer dollar work against it.
Views are as of the date above and are subject to change based on market conditions and other factors. These views should not be construed as a recommendation for any specific security or sector.
The Institute of Supply Management (ISM) manufacturing index is a composite, forward-looking index derived from a monthly survey of U.S. businesses.
Bond prices are sensitive to changes in interest rates and a rise in interest rates can cause a decline in their prices. In addition, fixed-income investors should be aware of other risks such as credit risk, inflation risk, call risk and liquidity risk. Credit ratings are subject to change and don’t protect against market.
High-yield, lower-rated securities generally entail greater market, credit, and liquidity risk than investment-grade securities and may include higher volatility and higher risk of default.
Foreign investing involves special risks including currency risk, increased volatility, political risks, and differences in auditing and other financial standards.
Yield Curve: Graph showing the comparative yields of securities in a particular class according to maturity. Securities on the long end of the yield curve have longer maturities.
Past performance is no guarantee of future results.
The performance quoted is for illustrative purposes only and is not representative of any specific investment.
For additional information, including definitions of related terms and indexes, see the Financial Glossary and Benchmark Index Glossary. In addition, by accessing documents containing CUSIP information, you agree to the Terms of Use for CUSIP Information contained in the Financial Glossary.
Although the information provided has been obtained from sources which Federated Hermes believes to be reliable, it does not guarantee accuracy of such information and such information may be incomplete or condensed.
The value of equity securities will rise and fall. These fluctuations could be a sustained trend or a drastic movement.
Prices of emerging-markets securities can be significantly more volatile than the prices of securities in developed countries and currency risk and political risks are accentuated in emerging markets.
There are no guarantees that dividend-paying stocks will continue to pay dividends. In addition, dividend-paying stocks may not experience the same capital appreciation potential as non-dividend-paying stocks.
Secured Overnight Financing Rate (SOFR): a broad measure of the cost of borrowing cash that is collateralized by U.S. Treasury securities. The New York Fed publishes SOFR on a daily basis.
Value stocks may lag growth stocks in performance, particularly in late stages of a market advance.
Growth stocks are typically more volatile than value stocks.
Small company stocks may be less liquid and subject to greater price volatility than large company stocks.
The value of some mortgage-backed securities may be particularly sensitive to changes in prevailing interest rates, and although the securities are generally supported by some form of government or private insurance, there is no assurance that private guarantors or insurers will meet their obligations.
Variable and floating rate loans and securities generally are less sensitive to interest rate changes but may decline in value if their interest rates do not rise as much or as quickly as interest rates in general. Conversely, variable and floating rate loans and securities generally will not increase in value as much as fixed rate debt instruments if interest rates decline.
Issued and approved by Federated Advisory Services Company. Federated Hermes and its subsidiaries are not affiliated with AmeriServ.